
Medical costs rise sharply with age, and a single hospitalisation can strain a family’s savings. Buying health insurance for parents and senior citizens is one of the most important financial steps a family can take. But senior citizen policies come with specific conditions — waiting periods, co-payments and sub-limits — that need careful reading before buying.
1. Why seniors need dedicated cover
Group cover from an employer may end at retirement, and many family floater policies have age or premium limitations. A dedicated policy for parents ensures continuity. IRDAI has removed the upper age limit for buying new health insurance, so insurers can offer policies to people of all ages, though terms vary.
2. Key features to compare
- Sum insured adequate for city hospital costs.
- Waiting period for pre-existing diseases such as diabetes or hypertension.
- Co-payment percentage the policyholder must bear.
- Room rent and disease-wise sub-limits.
- Network hospitals near the parents’ home.
- Coverage for day-care procedures and domiciliary treatment.
- Renewal terms and no-claim benefits.
3. Pre-existing diseases and disclosure
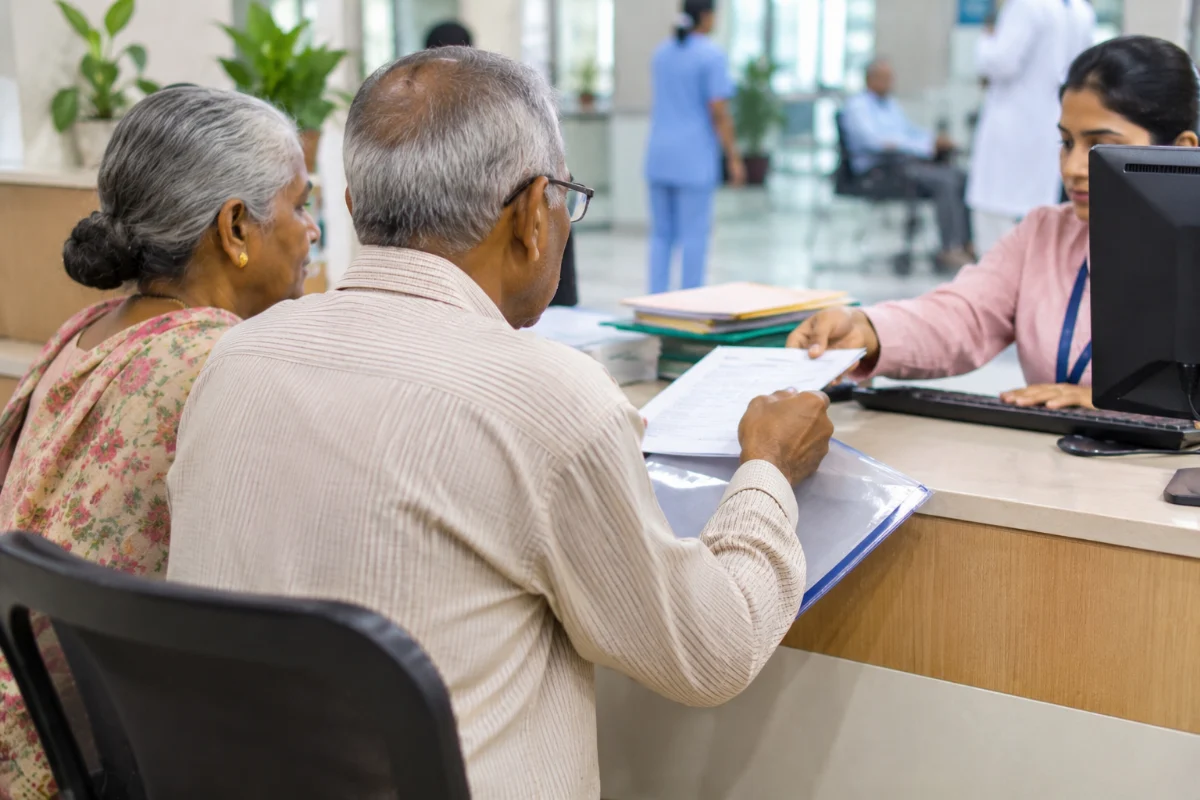
Disclose all existing conditions honestly in the proposal. Non-disclosure can lead to claim rejection. Waiting periods for pre-existing diseases apply as per the policy and regulations. Pre-policy medical tests may be required; preventive check-ups are explained by ATTPL Healthcare.
4. Managing premiums
Premiums for seniors are higher. Options to manage cost include choosing a base policy with a top-up or super top-up, accepting a reasonable co-pay, and buying early before health conditions develop. Compare value, not just price: a cheap policy with heavy sub-limits may leave large gaps.
5. Tax benefits
Under Section 80D, premiums paid for parents’ health insurance may be deductible within limits, with a higher limit if parents are senior citizens, under the old tax regime. Preventive health check-up expenses are included within the limit. Verify current limits with the Income Tax Department.
6. Common mistakes families make
- Choosing the cheapest policy without checking sub-limits and co-pay.
- Not disclosing existing illnesses.
- Letting a policy lapse and losing continuity benefits.
- Not informing parents and siblings how to use the policy.
- Buying too low a sum insured for city hospital costs.
Avoiding these mistakes makes the difference between a policy that helps in an emergency and one that disappoints.
7. Porting and renewal
Health insurance can be ported to another insurer at renewal while retaining eligible credit for waiting periods already served, subject to rules and the new insurer’s acceptance. Renew on time to keep continuity. Review the sum insured every few years as medical costs rise.
8. Government and public options
Some government health schemes cover eligible senior citizens and low-income families, and certain states run their own health insurance programmes. Check eligibility through official portals or local health offices, as such coverage can complement private insurance.
9. Claims and documentation
- Keep policy documents and health cards accessible to family members.
- Inform the insurer or TPA promptly for planned and emergency admissions.
- Prefer network hospitals for cashless treatment.
- Keep all bills, reports and discharge summaries.
Our claim process guide explains cashless and reimbursement claims. Elder legal rights are explained by ATTPL Legal.
Frequently asked questions
Is there an age limit to buy health insurance?
IRDAI has removed the upper age limit for buying new health insurance, though insurers set their own product terms.
What is co-payment?
The share of an admissible claim that the policyholder pays, as agreed in the policy.
Can I claim tax benefit for parents’ premium?
Under Section 80D, premiums for parents may be deductible within limits under the old regime; check current rules.
Can I port my parents’ policy to another insurer?
Portability is allowed at renewal, subject to IRDAI rules and the new insurer’s underwriting.
Sources
Need help choosing a health policy for your parents? Contact ATTPL Finance.